UK State Pension from Abroad Planner
Worked in the UK and now live abroad? Each missing year you fill adds about £358.50 a year to your UK State Pension for life, and a year costs £189.80 as Class 2 or £956.80 as Class 3. This spreadsheet goes through your whole record: which years you can still buy, at which class and price, the cheapest order, each deadline, what you keep where you live, and what you lose if you wait past 5 April 2027.
Free first: the headline answer
Our free voluntary NI from abroad calculator runs the same rules for the years you can still fill.
What is in the planner
- Start here. The answer for you and a partner side by side: qualifying years now and after, the pension before and after, the cost, the payback, what you keep where you live, and the cost of waiting.
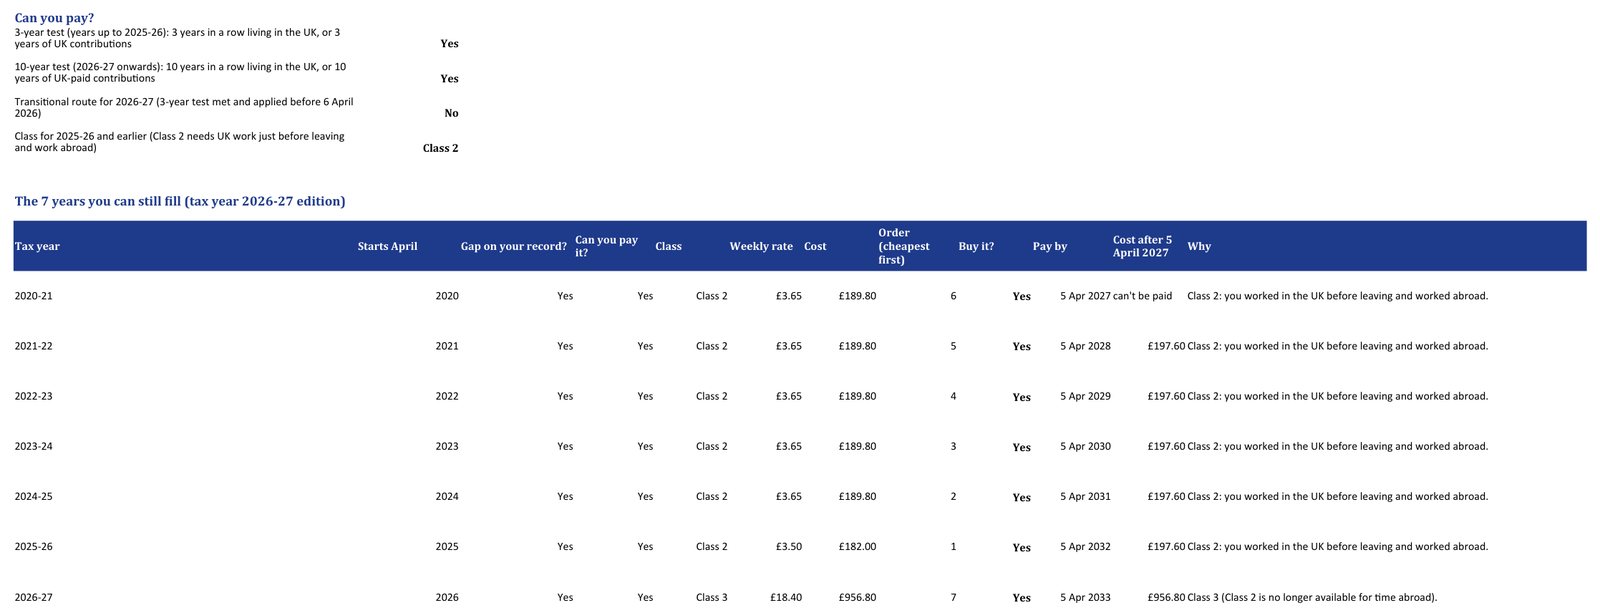
- You and Partner. Your record year by year from 1975–76, the 3-year and 10-year tests, and the 7 open years with class, weekly rate, cost, deadline and whether each is worth buying (cheapest first, never past 35 years).
- Where you live. Whether the pension rises each April there, what New Zealand Super, the Australian Age Pension, Canada’s GIS and the US take into account, and a rough lifetime value to 80, 85 and 90.
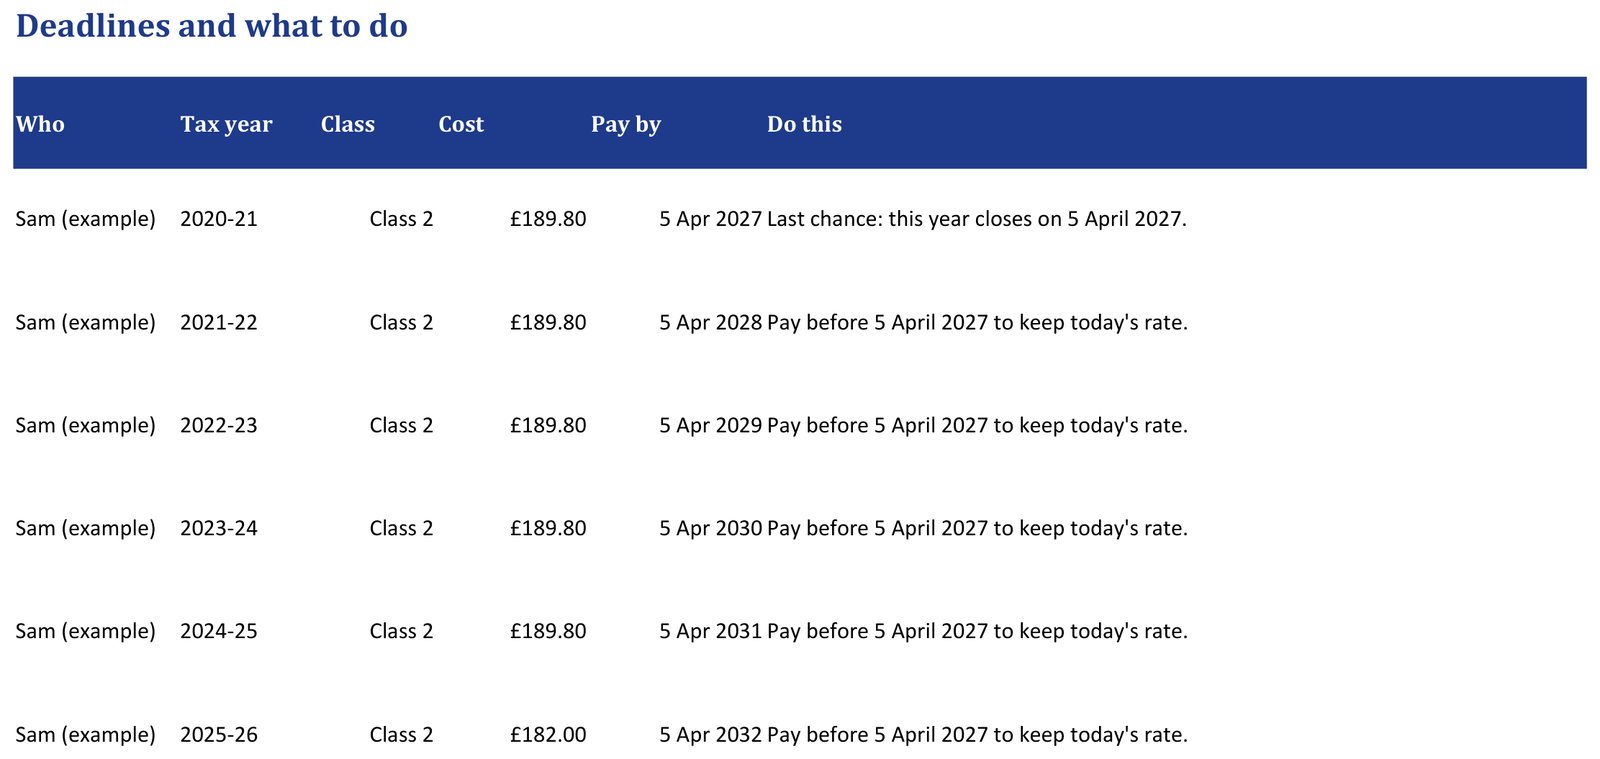
- Deadlines. Every year to pay and by when, your transitional-rule reminders, and the steps to apply with form CF83 and pay from abroad.
- Rules. Every rate and rule with its source. Change a figure in one cell when the 2027–28 rates are confirmed.
- A worked example (a separate, filled-in file).
The worked example
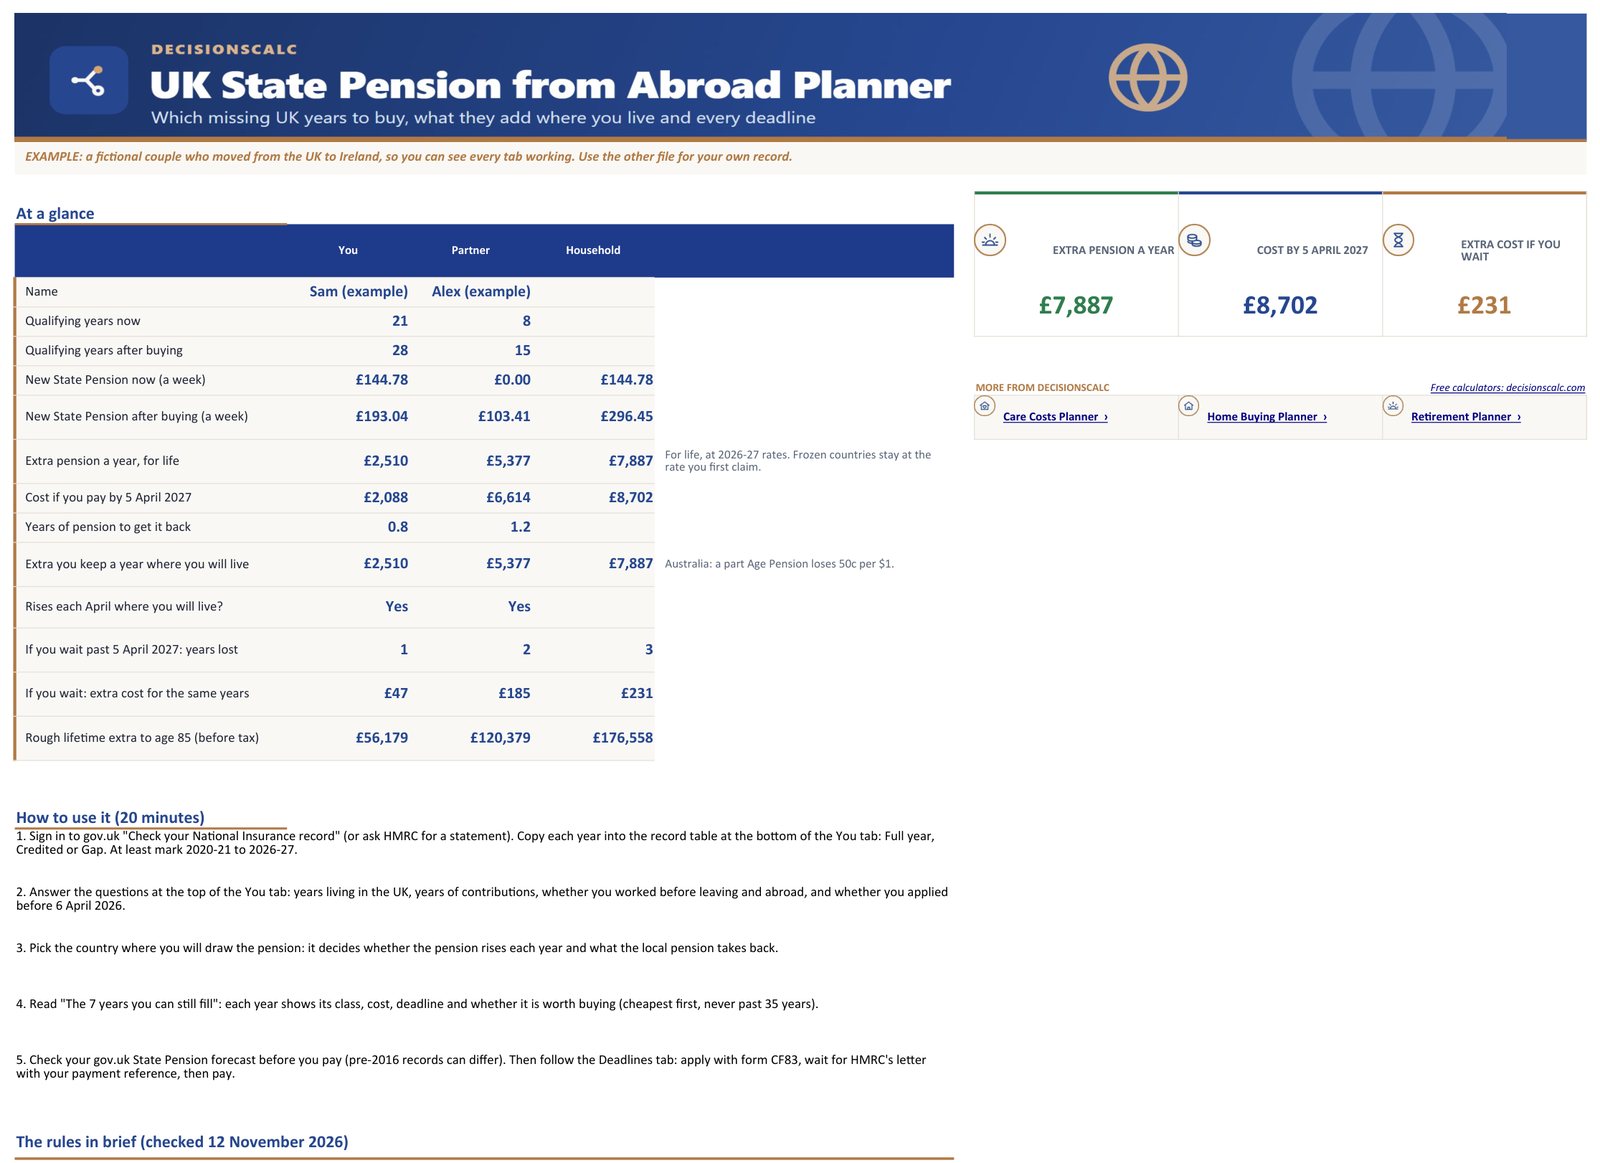
A fictional couple who moved from the UK to Ireland, where the UK pension rises each April.
| Example | The planner shows |
|---|---|
| Sam: 21 qualifying years, worked in the UK before leaving and in Ireland since | Buy 7 years for £2,087.80 (six of them at Class 2): £2,509.52 a year more for life, paid back in 0.8 years |
| Alex: 8 qualifying years, applied to pay Class 3 before 6 April 2026 | Buy 7 years for £6,614.40: past the 10-year minimum, so a pension of £5,377.32 a year instead of nothing |
| If they wait past 5 April 2027 | 3 years can no longer be bought (2020–21, 2020–21, 2026–27) and the rest cost £231 more |
See inside
Real pages from the worked example that comes with your purchase. Tap any page to see it full size.
Questions
- What does the planner do that the free calculator does not?
- It covers your whole record and keeps it. You copy each year from your gov.uk National Insurance record, and the planner works out which of the 7 open years you can still buy, at which class and price, the cheapest order to reach 35 years, each deadline, what you lose by waiting past 5 April 2027, what you keep where you will live, and a rough lifetime value. It does this for you and a partner in one file, with a Deadlines tab, the steps to apply with form CF83 and every rate on one Rules tab.
- Does it use the same rules as the calculator?
- Yes. The spreadsheet runs the same rules in ordinary formulas, and our tests recalculate it and check every year, class, cost and total against the website for 16 different households (Class 2 and Class 3, the 3-year and 10-year tests, the transitional rule, and each country).
- Which rules does it use?
- The 2026–27 rates (Class 2 £3.65 and Class 3 £18.40 a week, with the original rates for recent years), the full new State Pension of £241.30 a week, the 6-year deadlines, and the rules for time abroad from 6 April 2026 in The Social Security (Contributions) (Amendment No. 2) Regulations 2026 (SI 2026/294): no Class 2 abroad from 2026–27, the 10-year test for Class 3, and the transitional rule for people who applied before 6 April 2026. The 2027–28 rates announced at Budget 2026 (£19.05 and £3.80) are used for the “if you wait” figures and can be changed in one cell.
- I have years before 2016. Is the planner still right for me?
- The planner works out the pension as years/35 of the full rate. If you were contracted out, or have Additional State Pension, your starting amount can differ, and some voluntary years may not raise it. Check your State Pension forecast on gov.uk first; the planner shows which years to ask about.
- Does it work in Google Sheets?
- Yes. Upload the file to Google Drive and open it with Google Sheets. It also works in Excel (Windows and Mac), Numbers and LibreOffice. Standard formulas only, no macros.
- Is this financial advice?
- No. It is a planning tool built on published rules. HMRC decides whether you can pay and which class, and the Future Pension Centre’s forecast decides what you will get. Check both before you pay.
- What if it isn't right for me?
- Ask for a refund within 14 days and you get your money back, even after downloading. See the refund policy.
Rules read on 12 November 2026 on legislation.gov.uk (SI 2026/294), gov.uk Voluntary National Insurance, Paying National Insurance for time abroad, The new State Pension and State Pension if you retire abroad. General information, not financial advice.
Thank you!
Payment received. We're confirming it with Paddle, which usually takes a few seconds.
Keep this page's address (bookmark it): it's your personal download link, now and for future updates. Paddle has also emailed your receipt; if you lose this link, email hello@decisionscalc.com from that address and we'll resend it.
Open the planner and start on the Start here tab; the worked example shows every tab filled in. Opening in Google Sheets: upload the file to Google Drive, then open it with Google Sheets. Questions: hello@decisionscalc.com.